Mumbai: An unexpected 'Irish tonic' can liven up foreign investors put off by the Supreme Court's verdict that tipped tax scales against American investment firm Tiger Global.
In what could be a flicker of hope for many, a tax tribunal has spared a foreign company from capital gains tax on 'indirect transfer' of shares by seemingly skirting the apex court's stand in the . While direct transfer is a straight sale of shares of a company in India by an offshore investor, indirect transfer is the overseas sale of shares of another foreign company (maybe in another jurisdiction) holding equity in an Indian company. 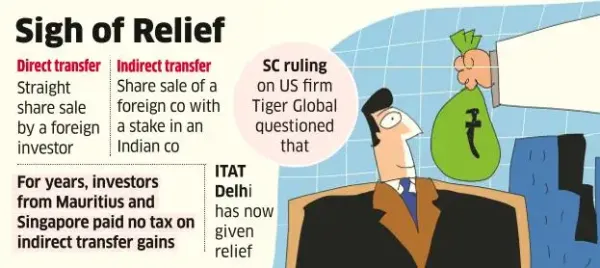 Since many foreign direct and portfolio investments have indirect structures, the tax impact of overseas deals linked to Indian stocks and assets holds significance for many. For years, it was widely perceived that indirect transfer gains aren't taxed for foreign investors from Mauritius and Singapore, the main gateways for inflows, as India's treaties with them make no specific mention of such overseas indirect transfer of Indian securities.
Though indirect transfer gains can be taxed under the Indian Income Tax (I-T) Act, foreign investors from treaty destinations escape it by deriving protection from treaties which prevail over domestic laws. However, in January 2026, the Supreme Court questioned this, saying that indirect gains of Tiger Global weren't protected from tax by the India-Mauritius treaty. A Tiger Mauritius entity had sold shares of its Singapore arm holding equity in an Indian company.
Also Read:
In its order released on September 30, the Delhi Bench of the (ITAT), a quasi-judicial authority, ruled in favour of an Irish company (Fireeye) by exempting it from paying tax on an indirect transfer transaction. Fireeye had sold shares in '21-22 of a US entity which was a shareholder in an Indian company. "Tribunal's decision seems to endorse the commonly accepted implication of taxation of indirect transfers from perspective. The same should apply to India's treaty with Singapore, Mauritius and others. Let's see how the High Court deals with this in the light of the Supreme Court ruling on Tiger Global," said Keyur Shah, head of tax India, Alvarez and Marsal.
In Tiger Global, SC had also questioned the adequacy of that foreign investors obtain from Mauritius authorities to claim treaty benefits. In giving relief to Fireeye, the Tribunal questioned the I-T department's decision to equate 'transfer' (as used in the I-T Act) with 'alienation' of shares as applied in the India-Ireland treaty.
According to chartered accountant Ashish Karundia, "It raises an important question on treaty interpretation. The SC three-judge bench decision in Vodafone held that where the law intends to cover indirect transfers, it says so expressly. The India-Ireland treaty does that in Article 13(4), but not in Article 13(5)/13(6). This suggests that the two provisions were intended to operate differently, with Article 13(5)/13(6) potentially covering only direct transfers. The ruling focuses on the expression 'alienation ', which is neither defined in the India-Ireland treaty nor in the I-T Act. Its meaning would need to be determined independently to ascertain whether it covers 'transfer'.
Also Read:
The India-Ireland treaty is in some ways similar to the one with Mauritius. While the India-Mauritius treaty defines 'alienation', most interpret it as akin to direct (and not indirect) transfer. Treaties generally use 'alienation' for sale of property, said Ashish Mehta, partner, Khaitan & Co. The real question, he said, where interpretational issues have arisen, is what was sold: shares of a foreign company holding Indian assets, or of an Indian company itself.
"The ruling reaffirms that domestic indirect transfer rules cannot blur that line. Considering the stakes involved, clarity from higher courts would be welcome," said Mehta.
Contact to : xlf550402@gmail.com
Copyright © boyuanhulian 2020 - 2023. All Right Reserved.